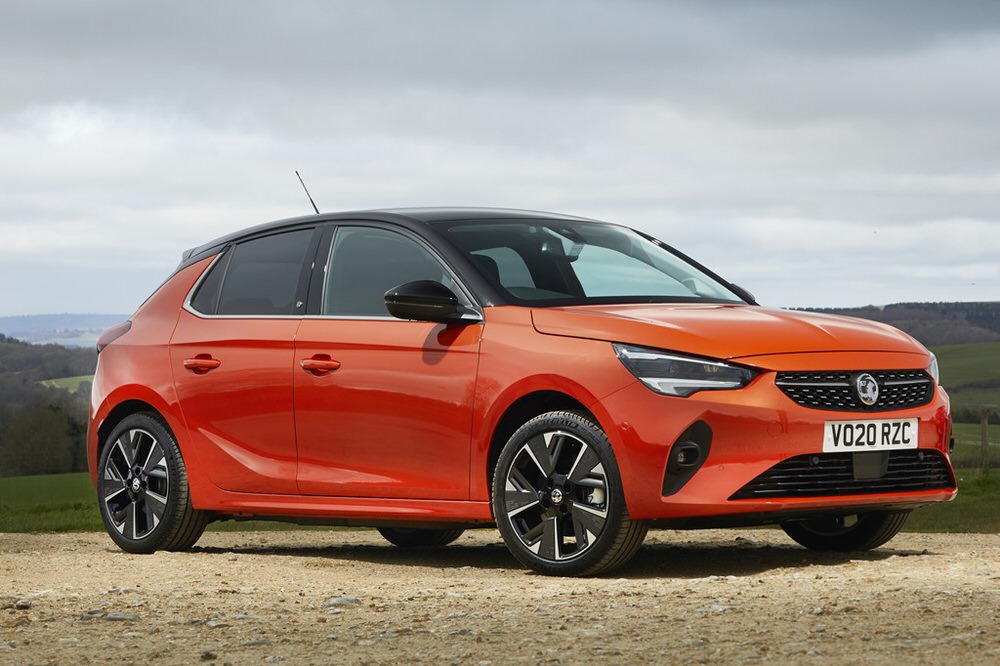
The Corsa keeps appearing in Motorly’s own guides as a first car recommendation. It comes up because the used market is enormous, running costs are low and there are enough examples around to compare properly before buying. The question most first time buyers have is what Vauxhall Corsa finance actually costs: new or used, PCP or HP. If you are a new driver, you can also read our guide to young drivers car finance.
New versus used Corsa on finance
A new Corsa currently starts at around £19,000, though the exact figure depends on trim, engine and any deals running at the time. Vauxhall periodically runs promotional Corsa finance deals in the UK, including 0% APR offers on certain models, so it is worth checking what is available rather than working from list price alone.
For a first time buyer, a used Corsa is often the more practical starting point. A three to five year old example will typically cost between £7,000 and £12,000 depending on mileage, trim and condition. That gap has a direct effect on what the finance looks like. Borrowing £9,000 produces a very different monthly payment from borrowing £19,000, even at the same APR and term.
A minor scrape on an £8,500 car is a different experience from the same mark on something that was brand new last month.
That said, the gap between new and used is not always as large as the sticker prices suggest. A manufacturer finance offer on a new Corsa can close the monthly cost difference. Always compare the total amount payable, not just the monthly figure.
PCP versus HP for a Corsa
Corsa PCP finance and Corsa HP finance work differently, and neither is automatically the better option.
With HP, you put down a deposit and pay fixed monthly instalments. When the last payment clears, the car is yours. The monthly payments are typically higher than the equivalent PCP deal, but the outcome is simple: you borrow the full purchase price minus your deposit and pay it back over the agreed term.
If you are buying a used Corsa to keep for several years and eventually sell privately, HP is usually the cleaner option. You own it. Sell it when you want, for whatever someone will pay.
Corsa PCP finance works by deferring a portion of the car’s value to the end of the agreement as an optional final payment. You only finance the rest in monthly instalments. This is why PCP payments are typically lower than HP on the same car. At the end you have three choices: pay the final amount and own it, hand it back, or put any equity towards your next vehicle.
PCP tends to suit a buyer who wants lower monthly payments and expects to change cars every few years. It works better with newer cars, where predicting a residual value is more reliable.
Compare the APR, deposit, monthly payment and total amount payable before deciding. The monthly figure alone does not tell you which option costs less overall.
Why the Corsa is such a common first car recommendation
The Corsa has been one of the UK’s bestselling cars for decades, and that history translates into one concrete advantage for first time buyers: choice.
You can compare dozens of different ages, mileages, trim levels and prices, rather than taking what happens to be available locally.
The dimensions matter for a first car. It fits parking spaces that would cause genuine difficulty in something larger, and it is practical enough for a daily commute, a motorway run or a weekly shop with two people and their bags.
Current petrol Corsas can return over 50mpg in official tests, though real-world figures will be lower depending on how and where you drive. Parts and servicing are widely available. There are so many on UK roads that most independent garages know the model well, which tends to keep repair costs competitive.
A small, affordable car does not automatically mean cheap insurance, particularly for a young or newly qualified driver. Your age, address, occupation, driving history and the exact model all play a part. Two Corsas from the same year with different trim levels or engines can produce very different quotes. Get a quote for the specific registration you are considering before you commit.
Corsa monthly payments vary more than most buyers expect, even between two people financing the same car at the same time.
The purchase price has the biggest effect. A £7,500 used Corsa and a £19,000 new one will not produce similar finance costs regardless of deposit or term. Age, mileage, trim and engine all affect the price you are financing.
Your deposit reduces the amount you borrow. A larger deposit lowers both the monthly payment and the total interest you pay. Whether putting more in upfront makes sense depends on your savings and what you will need in the first few months of ownership. Insurance, tax and servicing costs can arrive quickly.
Spread the borrowing over five years instead of three and the monthly payment drops, but you pay interest for longer and the total cost goes up. A shorter term hurts each month but costs less overall. The monthly figure alone is not a reliable guide to which deal is better value.
Your credit profile affects both the rate you are offered and which lenders will consider you. A clean history opens more of the panel. Missed payments or defaults narrow it. The rate difference can be several percentage points on a multi-year agreement. Check before you apply.
Motorly works with a panel of lenders rather than a single provider, which means we can look for options that fit your situation rather than applying to one lender and stopping there.
Applying through Motorly takes a few minutes, and the initial check will not affect your credit score.
You start by completing a short online application covering your personal details, employment, income and what you are looking for. That information helps match you against lenders on our panel.
Motorly then runs a soft credit search, which does not appear on your file or affect your score. You can see what is available before deciding whether to go ahead. If you choose to proceed with a specific lender, they may carry out a hard search as part of their application.
Once you have an idea of your budget, you can look for a Corsa that fits. You are not tied to a specific forecourt. Motorly works with a network of approved dealers, so you can find the right car rather than settling for what happens to be available.
Not automatically. Premiums depend on the specific car, your age, address, occupation and driving history. Two Corsas from the same year with different trim levels or engines can produce very different quotes. For a new driver, insurance can be large enough to change which car is the better overall deal. Get a quote for the exact registration before committing.
Can I get a used Corsa on finance with bad credit?
Potentially yes. A history of missed payments or defaults does not automatically prevent you from getting car finance. Motorly works with a panel of lenders, including those that consider applications from buyers with a range of credit histories. The rate and terms you are offered will depend on your individual circumstances. Finance is subject to status and affordability.
Is PCP or HP better for a Corsa?
It depends on what you want from the car. HP is often the better option if you plan to own the Corsa and keep it for several years. PCP may suit you better if lower monthly payments matter more and you plan to change cars at the end of the agreement. Compare the total amount payable as well as the monthly figure before deciding.
How much deposit do I need for a Corsa on finance?
There is no single figure. The deposit required varies by lender, finance product and your circumstances. A larger deposit reduces the amount you are financing, which lowers both your monthly payments and total interest. Keep enough in reserve for the other costs of running a first car: insurance, tax, fuel and servicing.
Is the Corsa better than the Fiesta for a first car?
There is no answer that applies to every buyer. Both are popular first car choices with large used markets. The Ford Fiesta was discontinued as a new car in 2023, so all Fiesta options are now used. When comparing individual cars, condition, service history, mileage, price and insurance cost will matter more than the badge. Get insurance quotes for both before deciding.
What is the cheapest way to finance a Corsa?
It depends on your circumstances. A used Corsa at a lower purchase price means borrowing less. A strong credit profile gives access to better rates. Occasionally, manufacturer finance offers on new Corsas can make the comparison closer than you might expect. When comparing deals, focus on the total amount payable rather than the monthly figure alone. The lowest monthly payment is not always the cheapest way to buy the car.
Searching for a car and arranging the finance have traditionally been two separate jobs. You might browse vehicles on one website, go somewhere else to explore your finance options, and then try to match what you can borrow with the car you want.
You can now browse thousands of used cars from dealers across the UK. You can filter the results by make, model, price, fuel type, gearbox and more. Once you’ve find the car you want, you can then apply for finance directly from the car you’re interested in.
Use the filters to narrow your search based on what matters to you. That could be a particular make and model, an automatic gearbox, a preferred fuel type or a price that fits your budget.
Each search result includes important information such as:
Price
Registration year
Mileage
Fuel type
Transmission
When you find a car you like, select it to view the full vehicle details. You can then begin a Motorly finance application from the vehicle page.
The car you’ve selected will automatically be included with your application, so you won’t need to enter its details separately.
What if you haven’t chosen a car yet?
You don’t need to find a specific vehicle before applying.
If you would prefer to explore your finance options first, you can complete an application without selecting a car. You can then search for a suitable vehicle once you have a clearer idea of your available options.
What cars are available?
Our search includes a wide range of used vehicles from dealers across the UK, with the stock feed updated regularly.
Whether you’re looking for a practical family car, buying your first car or planning an upgrade, you can use the available filters to focus on the vehicles that meet your requirements.
We’ll continue to improve the search and add more features as it develops.
Start your car search
Visit motorly.co.uk/cars/ to see what’s currently available.
If you find a car you’re interested in, select Check finance option and we’ll take you through the Motorly application. It only takes a few minutes to complete, and checking your options won’t affect your credit score.
If you have any questions, get in touch with the Motorly team and we’ll be happy to help.
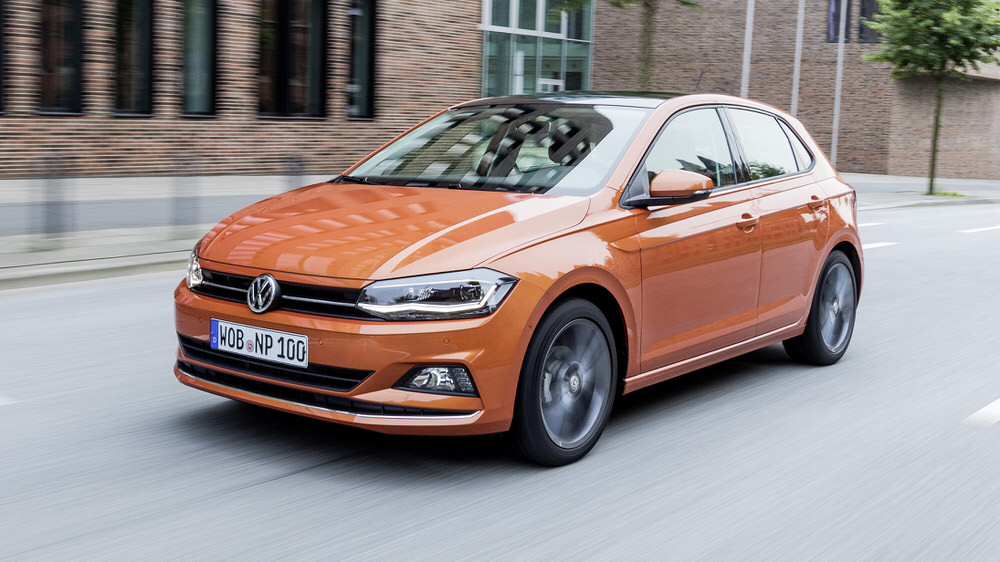
The Polo sits just below the Golf in VW’s range, and for a lot of buyers that is exactly the point. It is smaller, cheaper to insure and easier to finance affordably. Whether you are considering a new Polo on PCP or used Volkswagen Polo finance through a broker, this guide covers what you would actually pay, not just the deal of the month.
New versus used Polo on finance
A new Volkswagen Polo starts at around £22,000 for the entry-level trim as of July 2026, with higher specifications pushing closer to £27,000 to £29,000 before extras are added. Prices shift quarterly as VW updates its range and promotional offers.
Manufacturer deals can narrow the effective cost of going new. Volkswagen has been offering deposit contributions of between £2,750 and £3,250 on selected Polo models, with loyalty contributions available to existing Volkswagen Finance customers. These are model-specific and subject to change, so check what is current when you buy.
On the used market, a 2021 Polo typically sells for between £9,500 and £14,000 depending on mileage, engine and condition. Examples from 2023 are more commonly listed between £12,500 and £16,000. That drop from new list prices usually produces a lower monthly payment even when the APR on used finance is higher than a promotional PCP rate.
A nearly-new Polo, typically one or two years old, sits between both options. You absorb less of the initial depreciation hit than buying new, but the car is recent enough to carry current safety features and, in some cases, remaining manufacturer warranty.
A new Polo PCP with a strong deposit contribution and a high optional final payment can sometimes produce a monthly cost close to a used Polo on HP, even though the headline price is significantly higher. Always compare the total amount payable over the full term, not just the monthly figure.
Personal Contract Purchase and Hire Purchase are the two most common finance routes for a Polo. Which suits you depends on what you want at the end of the agreement more than the headline monthly cost.
How Polo PCP works
With PCP, part of the car’s value is deferred to the end of the agreement as an optional final payment, sometimes called a balloon. Your monthly instalments cover the depreciation and interest on the amount borrowed, not the full purchase price. That is what keeps PCP payments lower than HP on the same car.
At the end of the term you have three choices: pay the optional final payment and keep the Polo, return the car within the agreed mileage and in good condition, or use any equity in the vehicle toward another agreement.
The Polo’s residual values tend to be reasonably strong for a small car. A higher predicted future value means more of the purchase price can be deferred, which reduces your monthly payment.
PCP works well if you know your annual mileage and plan to change vehicles at the end of the term. Exceeding the mileage limit costs money per mile, and the car needs to be in good condition if you plan to return it.
How Polo HP works
With Hire Purchase, the price minus your deposit is divided across the term with interest added. There is no optional final payment. Once the last instalment is paid, the car is yours.
Monthly payments on HP are higher than PCP on the same car because nothing is deferred. HP agreements do not typically carry mileage limits, which makes them better suited to drivers who cover more miles or want to keep the car for several years. For a used Polo through a broker, HP is the standard product.
There is no standard Polo monthly payment. The amount varies depending on the car, the finance product and your circumstances.
The price of the car has the biggest influence. A used entry-level Polo will cost considerably less to finance than a new R-Line or GTI. Age, mileage, trim level and gearbox all affect the vehicle price, and automatic models generally carry a premium over equivalent manual versions.
Your deposit reduces the amount borrowed. On used finance, this might come from savings, a part-exchange or a combination of both. On a new PCP deal, a manufacturer deposit contribution effectively supplements your own, though it is typically tied to a specific product, term length and order window.
The agreement term determines how many months you spread the balance across. A longer term lowers the monthly payment but increases the total interest paid. Most agreements run from 24 to 60 months.
The interest rate can make a large difference to the total cost. Promotional new-car PCP rates are sometimes available but tied to specific models and quarters. Used finance APRs vary by lender, vehicle age and your credit profile. Always compare the total amount payable, not just the monthly figure.
Your credit profile affects which lenders will consider your application and on what terms. A stronger profile typically gives you access to better rates and a wider lender choice. A weaker profile does not automatically mean a refusal, but the rate offered may be higher and a larger deposit may be requested.
Is the Polo a good first car on finance
The Polo comes up regularly as a first car recommendation, and there are practical reasons for that.
It is compact enough for town driving and easier to park than a Golf or larger hatchback, but has five doors and enough interior space for passengers and shopping. That combination makes it practical for everyday use without feeling like something you will quickly outgrow.
Most versions use 1.0-litre or 1.5-litre petrol engines. The smaller units deliver reasonable fuel economy for mixed driving, which helps keep monthly running costs in check.
Insurance is where first-time buyers often get caught out. The Polo covers a wide range of insurance groups across its model range. An entry-level version with a 1.0-litre engine sits toward the lower end of the scale; a Polo GTI sits considerably higher. Get an insurance quote for the exact registration you are considering before committing to finance, not a general estimate for the model. A monthly payment that looks manageable can quickly become harder to sustain once insurance is added.
Budget for fuel, road tax, servicing and tyres alongside the finance payment. The Polo has a solid reliability record on the used market, but before you buy, confirm the service history, MOT records, whether any outstanding finance is recorded against the car and whether it has previously been written off.
Motorly searches across a panel of lenders rather than routing your application to a single finance house. That gives your application a wider assessment and a better picture of what is available for your circumstances.
Complete the online application with details about yourself, your income and what you are looking for; you do not need to have found a specific Polo before you start. Motorly then runs a soft credit search against its lender panel to check your initial eligibility. This does not affect your credit score, and a hard search only follows if you choose to proceed with a lender. Once you have a finance option confirmed, you can search for a suitable used Polo from an approved dealer, comparing vehicles on specification, mileage and price without being tied to one dealership’s stock.
Usually, yes. The Polo’s lower purchase price typically means a lower amount borrowed and a lower monthly payment. The gap can narrow depending on deposit, term, APR and whether a specific Golf deal carries a larger manufacturer contribution. Compare the total amount payable rather than the monthly headline.
Can I get a used Polo on finance with bad credit?
You can apply. Lenders assess your income, affordability, recent payment history and existing commitments rather than treating poor credit as an automatic bar. You may be offered a higher APR or asked for a larger deposit. Checking eligibility through a soft search first lets you see what may be available without affecting your credit score.
Is PCP or HP better for a Polo?
PCP tends to suit buyers who want lower monthly payments and plan to change the car at the end of the term. HP tends to suit buyers who want to own the car outright, are not concerned about mileage limits and plan to keep it long term. The right choice depends on your situation and the specific agreements available to you.
How much deposit do I need for a Polo on finance?
It depends on the lender and the product. Some agreements are available with a small or no customer deposit, though this is less common. Paying more upfront reduces what you borrow and lowers the monthly payment. A low-deposit agreement is not always cheaper once interest is factored in, so compare the total amount payable as well as the monthly figure.
Is the Volkswagen Polo a good first car?
It can be. It is compact and practical, with a broad choice of engines across the used market. The main things to check are the insurance cost for the exact registration you are buying and whether the full monthly budget, covering finance, insurance, fuel and servicing, is manageable.
What insurance group is the Volkswagen Polo in?
It varies significantly across the range. Lower-powered versions with smaller engines typically sit in lower groups. Performance variants such as the GTI sit considerably higher. Always check the insurance group for the exact car rather than the model in general, as two Polo models of different ages or trim levels can have very different premiums.
Vehicle prices and finance offers referenced in this guide are based on publicly available information as of July 2026 and may have changed. Finance is subject to status, affordability and lender approval. Terms and conditions apply.
Bad credit finance is not limited to cars. Specialist lenders consider motorbike applications from riders with CCJs, defaults, missed payments or a limited credit history, including bad credit motorcycle loans for riders turned away by mainstream providers. A low credit score does not automatically end the conversation, though it does affect which lenders will consider your application and on what terms. You can read more about bad credit vehicle finance and how specialist lending differs from a standard application.
What bad credit actually means for a motorbike application
“Bad credit” covers a range of different situations, and lenders do not necessarily treat them all the same way.
A missed payment from two years ago is a different situation from several missed payments in recent months. A settled default may be viewed differently from an outstanding balance. Someone with no UK credit history has no evidence of managing credit, but that is different from having repeatedly missed agreed payments. An IVA in progress sits in a different position to a CCJ satisfied several years ago.
Lenders outside mainstream criteria tend to look at the detail underneath the headline score: what type of problem, when it happened, how much was involved, whether it has been resolved and how your finances have been managed since. Motorly works with a panel of lenders that includes those prepared to consider applications that may not meet standard criteria, which makes it worth checking your options before assuming the door is closed.
Your current affordability matters too. A lender will want to know whether the proposed monthly payment is manageable alongside housing costs, household bills, existing borrowing and other regular commitments. Two people with similar scores can receive different decisions because their circumstances differ.
Can you get motorbike finance with a CCJ or a default
It may be possible, but the details affect which lenders will consider your application.
How old is the issue?
A CCJ remains on the Register of Judgments, Orders and Fines for six years unless paid in full within one month of the judgment. Payment after that point can be recorded as satisfied, but the entry generally stays on the register for the rest of the six-year period.
Defaults also generally remain on a credit file for six years from the date they were registered, regardless of whether the balance has since been paid. A lender is likely to ask when the problem occurred, whether the balance has been settled, whether it was isolated or part of a wider pattern, what your payment conduct has looked like since and whether there is a reasonable explanation.
A CCJ satisfied three years ago followed by clean payment history since presents a different picture to an unpaid CCJ registered a few months ago.
Does paying it off guarantee acceptance?
No. Settling a debt removes the outstanding balance, not the record of the problem. A satisfied entry can be viewed more positively than an unresolved one, particularly alongside stable income and a cleaner recent track record, but it does not guarantee approval.
Some lenders may still decline where the problem is recent. Others may consider it but offer a smaller advance, require a deposit or price the risk into the interest rate.
The underlying principles are similar to those that apply to car finance. Our guides to car finance with defaults and CCJ car finance cover what lenders are actually looking at in more detail.
See your options with a soft search, no impact on your credit file.
How lenders actually assess a bad credit motorbike application
Mainstream lenders often operate within defined automated criteria. An application that falls outside those parameters may be declined quickly, even where the applicant can comfortably afford the payments.
Specialist lenders may take a broader view. Credit history is still part of the assessment, but it can be considered alongside affordability and present circumstances rather than used as the primary filter.
A lender may examine your employment status and income, residential stability, existing credit commitments, recent payment conduct, the age and nature of any adverse credit entries, the value of the motorbike and whether a deposit is being provided.
Motorbike finance has one factor that does not apply to car applications in the same way: you must be legally entitled to ride the bike you are financing. Depending on engine size and power, this may require a valid CBT certificate or an AM, A1, A2 or full category A licence. A lender or dealer may ask for evidence of your entitlement before completing the agreement. (GOV.UK) Choosing a bike that matches both your licence and your budget can make the application simpler.
An initial eligibility check may use a soft search, which does not affect your credit score and is not visible to other lenders in the way a full application search is. (MaPS) A hard search may be carried out if you proceed with a full application. This should be explained during the process.
Does financing a motorbike help rebuild your credit
It can, but the conditions matter.
When a lender reports the agreement to the credit reference agencies and every payment is made on time, that creates a record of consistent borrowing. Over time, that sits alongside older problems on your file and gives lenders a more recent picture of how you manage credit.
There are limits worth being clear about. Taking out motorbike finance does not remove a CCJ, default or missed payment from your file. There is no guaranteed improvement to your score within a defined period, and different lenders and credit reference agencies use different scoring models. The effect on your file will depend on existing balances, recent applications, electoral roll registration and payment history across other accounts.
Missing payments on the new agreement makes the situation worse. The aim should be to finance a suitable motorbike at a manageable monthly cost. Any improvement to your credit history is a potential longer-term benefit, not a reason to take an unaffordable agreement.
What to expect on rate and deposit
Bad credit bike finance in the UK will usually carry a higher interest rate than finance offered to someone with a clean file. The APR a lender quotes reflects their assessment of the risk, taking in your credit history, income, deposit and the agreement being proposed.
This makes it important to look beyond the monthly payment. Before accepting any offer, check the cash price of the motorbike, the deposit, the total amount being borrowed, the APR, the monthly payment, the number of payments, the total amount repayable over the full term, any fees or final payment and what happens if a payment is missed.
The role of a deposit
A deposit reduces the amount you need to borrow. For some lenders, a lower loan-to-value can also signal lower risk. Putting money down will not erase adverse credit history, but it may improve the overall shape of the deal. Do not use money needed for rent, bills or an emergency simply to maximise the deposit. A smaller, sustainable deposit is more useful than an overextended one.
Guarantor finance
Some lenders offer guarantor-based finance, though not all products include it. A guarantor agrees to make the payments if the borrower does not. That is a significant legal and financial commitment, not a character reference. The guarantor will need to meet the lender’s own eligibility requirements. Having a guarantor may widen the available options but does not guarantee approval.
How to improve your chances
You cannot rewrite your credit history before applying, but you can make sure the application reflects your current position accurately.
Check your credit file with the main UK credit reference agencies before applying. Look for incorrect address associations, accounts you do not recognise, defaults marked as unpaid that have since been settled or duplicated entries. Dispute anything inaccurate with the relevant organisation. The score is a headline figure; the underlying detail is what matters.
If you have had a vehicle repossessed previously, check whether the sale of that vehicle settled the outstanding finance balance. When a lender sells a repossessed vehicle for less than the outstanding loan, a shortfall balance may remain. An unresolved balance from a previous vehicle agreement can make a new lender more cautious. Check the position with the previous provider and confirm that any payments or arrangements are correctly recorded.
Keep your payment conduct clean in the period before applying. Recent behaviour carries weight. Try to make all current payments on time and avoid submitting several full credit applications in quick succession. Each formal application can result in a hard search, and multiple searches in a short period may suggest you are urgently seeking credit.
Choose a realistic bike. A smaller loan amount simplifies the application, reduces the monthly payment or the term and leaves room in your budget for insurance, servicing, tyres and protective equipment. Approval for a bike that is beyond your present budget would not be a good outcome.
Check your eligibility for motorbike finance in minutes.
How to apply for bad credit motorbike finance with Motorly
Motorly connects applicants with a panel of finance providers, including specialist lenders that consider a range of credit histories.
Complete the online application
Provide your personal details, income, address history and the type of motorbike finance you are looking for. Accurate information gives lenders what they need to assess the application properly.
See your potential options with a soft search
Your details are matched with lenders whose criteria are more likely to fit your circumstances. The initial check uses a soft search, so it does not affect your credit score and will not be visible to other lenders.
Review any finance offered
If a lender is able to make an offer, review the APR, the monthly payment, the term and the total amount repayable before deciding whether to proceed. A hard search may be carried out when you make a full application.
Finance is subject to status, affordability and lender criteria. Not every application will be approved, and the rate available to applicants with adverse credit may be higher.
Apply for motorbike finance with lenders who consider bad credit applications.
Can I get motorbike finance with a CCJ or default?
Potentially. Some specialist lenders consider applications from people with CCJs or defaults. A lender will usually look at when the problem occurred, how much was owed, whether it has been satisfied and how you have managed your finances since. Approval is not guaranteed.
Does a low credit score automatically rule me out for bike finance?
Not automatically. Lenders do not all use the same scoring model or acceptance criteria. Income, affordability, existing commitments and recent payment conduct are all considered alongside your credit history. A low score may reduce the number of available lenders or result in a higher rate, but many applicants with poor credit history are approved.
Will applying affect my credit score?
An initial soft-search eligibility check does not affect your credit score. A hard search may be carried out if you proceed with a full application. Check what type of search will be used before submitting your details.
Do I need a deposit for bad credit motorbike finance?
That depends on the lender and the application. Some agreements may be available without a deposit, while others will require one. A deposit reduces the amount borrowed and may improve the terms available, but it does not guarantee approval.
Can financing a motorbike help my credit score?
It may help build a more positive recent credit history if the lender reports the agreement to the credit reference agencies and every payment is made on time. There is no guaranteed score increase or fixed timeline, and missing payments could damage your credit position further.
What licence do I need to get motorbike finance?
You need the appropriate entitlement for the bike you intend to ride. This may be a valid CBT certificate for smaller machines or an AM, A1, A2 or full category A licence, depending on engine size, power and your age. The lender or dealer may ask for evidence before the agreement is completed.
Motorly is a credit broker, not a lender. We can introduce you to lenders from our panel. Finance is subject to status, affordability and lender criteria. Terms and conditions apply. Confirm the exact regulatory disclosure and representative example with your compliance contact before publishing.
Pay monthly cars sounds like its own category, as if the seller knows about some special route around a credit check. In nearly every case it means standard hire purchase or PCP finance, described in the words people search for rather than the terms lenders use. It does not bypass credit checks, and it is not the same as pay as you go finance even when bad credit is behind the search. Understanding the difference changes what you are agreeing to.
What pay monthly cars actually means
Most pay monthly car adverts are not describing a separate finance product. They are using everyday language to describe standard car finance.
Pay monthly car finance usually means one of two things. You apply through a dealer that arranges its own finance, or you apply through a broker that checks a panel of specialist lenders. Either way, if accepted, you repay the amount borrowed in monthly instalments over an agreed term.
The agreement behind those monthly payments is usually hire purchase (HP) or personal contract purchase (PCP).
With HP, your monthly payments cover the cost of the car plus interest across the full term. Once the final payment is made, the car is yours.
With PCP, monthly payments are usually lower because a larger portion, called the optional final payment or balloon, is held back until the end of the agreement. At that point you choose whether to pay it and keep the car, hand the car back, or use any equity towards a new vehicle.
Neither of these is unusual or exclusive to bad credit customers. HP and PCP are the two most common ways to finance a car in the UK. Pay monthly is simply how that is described to people who are not thinking in lender terms.
A lender still checks your credit file, assesses affordability and decides whether to offer finance.
Pay monthly versus pay as you go: not the same thing
Pay monthly and pay as you go car finance are regularly treated as the same thing online. They are not.
Pay monthly car finance is standard HP or PCP. You apply, get accepted and repay in fixed monthly amounts. You are usually recorded as the registered keeper from the start of the agreement, though the finance company retains ownership of the vehicle until it is paid in full.
Pay as you go car finance is a more specialist arrangement, typically aimed at customers who may not qualify for standard finance because of more serious credit problems. It often involves a payment device or black box fitted to the vehicle, which can be used to restrict or disable the car if payments are missed. The pool of lenders is narrower, and the choice of cars and dealers may be more limited.
If you searched for pay monthly cars with bad credit and ended up here, it is worth checking what the advert you saw was actually describing. If it mentioned a black box, a payment device, or a rental-style arrangement, it may have been a pay as you go product rather than standard car finance. Motorly’s guide to pay as you go car finance covers that route if that is what you were looking for.
Does pay monthly mean no credit check?
No. There is no such thing as no credit check car finance in the UK.
Any FCA-regulated lender is required to assess whether credit is affordable and suitable before offering it. That means checking your income, your outgoings and your credit history.
Where the confusion comes from is the difference between a soft search and a hard search.
Many pay monthly car finance adverts lead with a soft search first. A soft search can be used to check your eligibility without leaving a visible mark on your credit file for other lenders to see. This is often what adverts mean when they say “no impact on your credit score” or “check without affecting your credit file”.
That is not the same as no credit check.
A soft search still looks at your credit history. It does not affect your file in the way a hard search does, and other lenders cannot see it. But it is still a check.
A hard search happens later, when you move forward with a full application or finance agreement. Hard searches are visible to other lenders and can affect your credit score, particularly if you make several applications close together.
Soft search first is a real thing, and it is how many pay monthly brokers actually operate. No credit check car finance is not. There is more on what credit score you need for car finance if you want to understand how scoring works before you apply.
What lenders actually look at when bad credit is in the picture
When bad credit is on your file, lenders pay closer attention to what is behind it.
They are not working from a single credit score. The score is a summary, and what they look at in more detail is the type of credit problem, how recent it is and whether it has been resolved.
A missed payment from several years ago carries less weight than several recent ones. A default that has been settled looks different from one that is still outstanding. A satisfied CCJ is not the same as one that remains unpaid. The timing and the current status of any issues on your file are what lenders are actually assessing.
Beyond the credit file, lenders look at your income, your existing monthly commitments and how much disposable income you have after essential costs. They want to know whether the agreement is affordable, not just whether you have ever had a problem with credit.
A deposit can help. It reduces the amount you are borrowing and can lower the lender’s risk. But it does not automatically compensate for affordability concerns. If the monthly payments look unaffordable relative to your income, a larger deposit may not change that.
The type of credit issue also makes a difference. Someone with a thin credit file, meaning they have not borrowed much before, is in a different position from someone with multiple recent defaults. Both may appear under the bad credit car finance umbrella in advertising, but lenders assess them differently.
The most common mistake when looking at pay monthly cars with bad credit is treating the monthly figure as the main measure of whether a deal is good.
A lower monthly payment can look appealing, but it is not a reliable indicator of value. It may simply mean the agreement runs over a longer term, carries a higher APR, or includes a larger final payment at the end.
Before committing to anything, look at the total amount payable. This tells you what the car will cost once interest, fees and all repayments are included. That is the number you are actually comparing between deals.
Check the APR. The representative rate in an advert is not always the rate you will personally receive. If your credit history is poor, your actual rate may be higher. Knowing it in advance is the only way to judge it fairly.
Term length is a real trade off. A longer term reduces the monthly amount but increases the total cost of credit, and it can leave you still paying for the car long after its value has dropped.
If the agreement is PCP, check the mileage limit, the final payment amount and what happens at the end. Many people focus only on the monthly figure and find themselves caught out by a balloon payment or condition charges when the agreement closes.
It is also worth checking who is arranging the finance. A single dealer’s in house option may only have access to one lender or a small panel. A broker with a wider lender panel can check more routes, which matters if your credit file has complications, because different lenders apply different criteria. The bad credit car finance direct lender guide explains when going direct may or may not work in your favour.
A poor deal is not always the one with the highest monthly payment. It is the one where you do not understand what you are paying, what happens if your circumstances change, or what the car will actually cost by the end.
How to apply for pay monthly car finance with Motorly
Motorly is a broker, not a single lender. That means your application is checked against a panel of lenders rather than a single in house option.
The process works in three steps.
First, you complete an online application with your personal details, employment, income and the type of car you are looking for. This gives lenders the information they need to assess your circumstances.
Second, Motorly runs a soft search first. You get an indication of what may be available without a hard search appearing on your credit file at that stage.
Third, if you are accepted and want to proceed, you can buy a new or used car from any approved dealer. You are not tied to one forecourt or one dealer’s stock.
This matters if your credit file has complications, because lender criteria vary. An application one lender declines may be one another is prepared to consider. Motorly matches your application with lenders whose criteria suit your circumstances.
You will need to be accurate about your income, employment, address history and financial position. Details that do not stack up will slow the process down or lead to a decline at a later stage.
Is pay monthly car finance the same as no credit check car finance?
No. Pay monthly car finance means standard car finance repaid in monthly instalments. It does not mean no credit check.
Some lenders run a soft search eligibility check as a first step, which lets you see what you might qualify for without affecting your credit file. That is not the same as skipping a credit check entirely.
Can I get pay monthly car finance with a CCJ or default?
Possibly, depending on the lender, the age and status of the CCJ or default, your income and the rest of your application.
A recent unpaid CCJ or default is likely to be assessed more strictly than an older, settled one. Lenders look at the full picture, not just whether a marker is present.
What is the difference between pay monthly and pay as you go car finance?
Pay monthly usually refers to a standard HP or PCP agreement with fixed monthly repayments.
Pay as you go car finance is a more specialist product, often involving a payment box fitted to the car. It is typically aimed at customers who may not qualify for standard finance.
They are not the same, and it is worth checking which one an advert is describing before you apply.
Do I need a deposit for pay monthly car finance?
Some lenders offer finance without a deposit, depending on your circumstances.
A deposit can help because it reduces the amount you are borrowing and may lower the lender’s risk. Whether it makes a material difference depends on the rest of your application.
Will applying for pay monthly car finance affect my credit score?
A soft search eligibility check should not affect your credit score.
A hard search may follow later if you proceed with a full application or finance agreement. Hard searches are visible to other lenders and can affect your score, particularly if you apply to several places in a short period.
Always check whether the first step is a soft search before applying.
Is pay monthly car finance more expensive than a personal loan?
It depends. Personal loans may carry lower rates for people with strong credit, but they can be harder to obtain if your credit history is poor. Car finance is secured against the vehicle, so some lenders will consider applicants they would not approve for an unsecured loan.
The relevant comparison is the total cost of borrowing: APR, total amount payable, fees, term length and any final payment. The monthly figure alone is not enough to judge by.
Black box car finance comes up regularly when people are researching options after a decline or with a bad credit history. The name explains part of it, but not everything. There is a box and it is fitted to the car, but how it works, what happens if you miss a payment and whether you actually need one are all worth understanding properly before you look any further.
Motorly does not offer black box car finance directly. We work with a specialist bad credit hire purchase panel. The comparison is worth understanding before you apply for anything. For a quick overview of what Motorly offers, see our black box car finance page.
What is black box car finance?
Black box car finance is a type of hire purchase where a small electronic device is fitted to the car. The finance agreement works in the same way as standard HP. You pay a deposit if one is required, make fixed monthly payments over the agreed term and own the car outright once the final payment is made.
The black box is the main difference.
The device is fitted after your finance has been approved, by a qualified auto-electrician, usually in the glovebox or under the dashboard. It connects to the car’s internal computer and communicates with the lender via GPRS. Provided payments are made on time, you will not notice it is there.
Black box car finance is also called pay as you go car finance or PAYG car finance. The terms refer to the same product. If you have come across either phrase while researching bad credit car finance options, you are looking at the same thing. For more detail on the PAYG angle, see Motorly’s guide to pay as you go car finance.
Does the black box track your driving?
No. A black box fitted for car finance does not monitor how you drive. It does not record your speed, routes, braking, mileage or the times you use the car.
This is the most important distinction between a car finance black box and a car insurance black box. An insurance telematics device is designed to monitor driving behaviour and may affect your premium based on how you drive. A car finance black box is different. It tracks payment status, not driving behaviour.
The device communicates with the lender to receive payment status updates. In a missed payment scenario, it can also allow the lender to remotely immobilise the vehicle. It is not transmitting information about your journeys.
How the payment reminder system works
Three days before your monthly payment is due, the indicator light on the black box changes from green to red and begins to flash. Some lenders also send a text reminder at this point. The purpose is to prompt you before the due date, not to restrict your use of the car.
Once the payment is made, the lender sends a signal to the box and the light returns to green. Some lenders issue an activation code that you enter manually into the box to reset it. Either way, the process takes seconds and does not affect your ability to drive.
For most borrowers who keep up with their payments, that is all the black box does. The light goes red briefly each month and goes back to green once payment has been made.
What happens if you miss a payment?
If you miss a payment, the lender will try to contact you first. Most have a grace period of up to around 30 days during which they will attempt to reach you and resolve the situation before taking any further action. Missing one payment does not mean the car is immediately immobilised.
If the grace period passes without a payment or an agreed resolution, the lender can use the GPRS connection to remotely immobilise the vehicle. This means the car will not start the next time you try to use it. The system cannot cut out a moving vehicle. Immobilisation only ever happens when the car is stationary.
Once the overdue payment is made and the account is back up to date, the lender sends a reset signal and you regain full use of the car. If the situation cannot be resolved, the lender may move toward repossession, using the GPS function to locate the vehicle.
The immobiliser function is a real consequence of missed payments. Understanding it before signing is the clearest protection against ever encountering it.
Who is black box car finance designed for?
Black box finance is designed for people who may struggle to get approved for standard car finance because of adverse credit. The device gives lenders the security to approve applicants they would otherwise consider too high-risk. If payments stop, they have a mechanism to recover the vehicle without needing a court order.
The product is particularly relevant for people with heavily adverse profiles: recent CCJs, multiple unsatisfied defaults, a recent IVA or bankruptcy discharge, or a pattern of missed payments across several accounts. In these cases, the black box can be the difference between approval and decline. For more on your options with a CCJ, see Motorly’s guide to getting car finance with a CCJ.
It is also sometimes used by people who have had payment discipline issues rather than affordability issues. If you have missed payments in the past through disorganisation rather than financial difficulty, the built-in reminder has genuine practical value.
Is black box car finance more expensive than standard HP?
Yes, typically. Black box finance lenders are taking on higher-risk applicants, and the rates reflect that. The APR on a black box agreement tends to sit at the higher end of the subprime market.
The fitting of the box is covered by the lender, so there is no installation cost to you. But the interest cost over the full term is worth calculating carefully before you sign. A higher APR over a four or five-year agreement can mean paying significantly more in total than a lower-rate standard HP deal for the same vehicle.
This is one of the main reasons it is worth checking whether standard bad credit HP is available to you before committing to a black box agreement. If it is, it will almost always be the more cost-effective and less restrictive route.
Do you actually need a black box?
Black box finance is a legitimate product and for some borrowers it is the only realistic route into car finance. But it is not the only option for people with bad credit, and for many it is not the right starting point.
The specialist bad credit HP market in the UK is broad. Lenders in this space assess applications individually. They look at income, employment stability, how long ago adverse events occurred and what the trajectory has looked like since, rather than applying automated rules that result in a straight decline. A broker with access to a specialist panel can match your application to the right lender without requiring a black box.
Before pursuing a black box agreement, it is worth checking whether you can be approved for standard HP through a specialist panel. The check is free, uses a soft search that does not affect your credit file, and takes a few minutes. If a specialist lender can help, you avoid the black box entirely. If they cannot, black box finance remains an option.
It is also worth considering whether guarantor car finance might be available to you. If you have someone willing to support your application, that route can sometimes open up options before moving to black box finance.
Motorly does not offer black box car finance directly. We work with a specialist bad credit car finance panel that covers a wide range of adverse profiles, including people who have been declined elsewhere.
How to apply for bad credit car finance through Motorly
You can apply online in a few minutes. Your application goes to a panel of specialist lenders via a soft search, so there is no impact on your credit file until you choose to proceed with a specific offer. If a lender can help, you will receive a decision quickly and can choose your car from any approved UK dealer. There are no application fees.
If the panel cannot match your profile, you will know where you stand. Black box car finance through a specialist direct lender remains an option from there.
Does a black box for car finance track your driving?
No. A black box used for car finance does not monitor how you drive. It does not record your speed, routes, braking, mileage or journey times. The device is linked to payment status, not driving behaviour.
What happens if I miss a payment on black box car finance?
If you miss a payment, the lender will try to contact you first. Most have a grace period of up to around 30 days before any further action is taken. If the missed payment is not resolved within that period, the lender may use the black box to immobilise the vehicle while it is stationary.
Can the black box immobilise my car while I am driving?
No. Immobilisation only happens when the car is stationary. The system cannot cut out a moving vehicle.
Is black box car finance the same as pay as you go car finance?
Yes, in most cases. Black box car finance, pay as you go car finance and PAYG car finance are different names for the same type of HP agreement with a payment-linked device fitted to the car.
Can I get car finance with bad credit without a black box?
Yes, it may be possible. Many specialist HP lenders consider applicants with bad credit without requiring a black box. Whether you can be approved depends on your credit profile, income, affordability and the lender’s criteria.
How long is the black box fitted to the car?
The black box is normally fitted for the duration of the finance agreement. Once the final payment is made, the lender will confirm what happens next, including whether the device needs to be removed or deactivated.
Is black box car finance more expensive than standard HP?
It often is. Because black box finance is aimed at higher-risk applicants, the APR is typically at the higher end of the subprime market. That is why it is worth checking whether standard bad credit HP is available to you before committing to a black box agreement.
Who fits the black box and how long does it take?
The box is fitted by a qualified auto-electrician after your finance has been approved. It is installed in a discreet location such as the glovebox or under the dashboard. The exact timescale varies by lender.
Most articles about car finance with defaults tell you the same thing: yes, it is possible, specialist lenders exist and applying through a broker can help. That is true, and if that is what you need, the Motorly guide to car finance with multiple defaults covers your realistic options in more detail.
The specifics matter. What a default actually looks like on your credit file, how lenders read the details and what you can do before applying to improve your position are worth understanding before you approach a lender.
What a default actually looks like on your credit file
A default is recorded on your credit file when a lender formally marks an account as defaulted because the agreed repayments have not been kept up.
This usually happens after several missed payments. In many cases it follows three to six months of arrears, though the exact timing depends on the lender, the type of credit and the account history.
Before a default is registered, the lender will normally issue a default notice. This gives you a short period to bring the account up to date before the default is added to your file.
Once recorded, the default entry shows several specific details: the name of the lender, the date the default was recorded, the original amount of the debt, the current balance if any remains outstanding, and the account status. That status shows either that the default is still outstanding or that it has been satisfied.
This matters because lenders do not only see the word “default”. They see when it happened, how much it was for, whether it has been paid and what has happened on the rest of your credit file since.
A default stays on your credit file for six years from the date it was recorded. Paying it does not remove it. Instead, the entry is updated to show that the debt has been satisfied, which lenders view more positively than an unpaid default.
One detail that catches people out: the six-year clock runs from the default date, not from the date you pay the debt. A default recorded in January 2021 drops off your file in January 2027, whether you paid it in 2021 or in 2025. That timing matters when you are considering when to apply.
Satisfied vs unsatisfied defaults: what the distinction means for lenders
A satisfied default means the debt has been paid in full. The entry on your file shows a zero balance and a satisfied status. Lenders view this more positively than an unsatisfied default because it demonstrates the problem was resolved, even if it took time.
An unsatisfied default means the balance is still outstanding. When it comes to car finance with unsatisfied defaults, the pool of lenders willing to assess the application is usually smaller and the rates on offer are likely to reflect the higher risk.
If you have unsatisfied defaults and are in a position to clear them before applying, doing so can make a meaningful difference. It can increase the number of lenders willing to assess the application and may improve the rate you are offered.
Partially paying a default, or entering a payment arrangement with the creditor, does not update the status to satisfied. The default remains outstanding until the full balance is cleared. Partial payments may appear on the account history but the headline status that lenders see first will not change until the debt is fully paid.
How lenders read the pattern, not just the number
The number of defaults on your file matters, but it is not the only thing lenders look at. A lender is trying to read the story behind the credit file.
A cluster of defaults recorded within the same few months tells a very different story to defaults spread across several years. A cluster can suggest a single difficult period, such as a job loss, a relationship breakdown or a health crisis. If the credit file then shows stable payments afterwards, specialist lenders will often focus on what has happened since rather than treating each default as an independent failure.
Defaults spread across a longer period are harder to assess. They can point to sustained financial difficulty rather than a single event with a clear resolution. That makes it harder for a lender to identify a turning point where the borrower’s finances became stable.
Recency matters significantly. A credit file showing four defaults from three years ago, with clean payments since, is usually stronger than one showing a single default from eight months ago. Most specialist lenders weight recent behaviour heavily. The question they are asking is not whether you have ever had credit problems but whether you are likely to pay reliably now.
The Notice of Correction: what it is and when to use it
A Notice of Correction is a short statement, up to 200 words, that you can add to your credit file to explain the circumstances behind an adverse entry. You can add one through any of the three main credit reference agencies: Experian, Equifax or TransUnion.
It does not remove a default or change the date, amount or status of the entry. What it can do is give lenders context. If your defaults were caused by a specific, time-limited event such as redundancy, illness or a relationship breakdown, a Notice of Correction lets you state that plainly in your own words.
Not all lenders will read it. Those using automated decisioning may give limited weight to added notes. Specialist lenders with manual underwriting are more likely to take it into account.
Worth adding if the circumstances are genuine and clearly explainable, though it is not a substitute for paying debts where possible, allowing time to pass and keeping a clean payment record since.
What else lenders look at alongside defaults
Defaults are one input into a car finance decision, not the whole picture.
The time elapsed since the most recent default matters. Most specialist lender assessments begin to open up meaningfully once defaults are 12 months or more in the past, and improve further at the two and three year marks.
The rest of your credit file matters too. A file with defaults alongside a CCJ, an IVA and ongoing missed payments tells a very different story to one where defaults are the main adverse entry and recent credit behaviour is otherwise clean. If you also have a CCJ, the 2026 guide to CCJ and car finance cover how lenders assess that separately.
Income and affordability carry significant weight. Stable, provable income that comfortably covers the proposed monthly payment is one of the strongest positive signals available, regardless of the credit history on the file.
A deposit can also help. Putting money down reduces the amount the lender needs to finance, which can improve both the likelihood of approval and the rate on offer.
Being registered on the electoral roll at your current address is a basic credibility signal. If you are not registered, it costs nothing to sort before you apply.
How long do defaults affect your car finance options?
Defaults stay on your credit file for six years, but their practical effect on what is available to you changes over time.
In the first six to twelve months, mainstream lenders are likely to decline. Specialist lenders may still consider applications, particularly where income is stable and the default has been satisfied, but the pool is narrow and rates will reflect the risk.
At one to two years, specialist lender options begin to widen, particularly where the payment record since the default has been clean.
At two to three years, most specialist bad credit lenders will assess applications normally. Rates start to improve as the defaults age.
At three to five years, many applications move into near-standard specialist lending territory, assuming the rest of the file is stable and affordability works.
At six years, the default drops off your credit file entirely.
Before applying for car finance with defaults, check what lenders are actually going to see. Do not rely on a general sense of your credit history. Look at the specific entries on your file.
All three credit reference agencies offer free access to your statutory credit report: Experian, Equifax and TransUnion. It is worth checking all three. Defaults are not always recorded identically across every agency and lenders may use any of them.
Look at whether each default is marked satisfied or unsatisfied, whether the dates and amounts are accurate and whether there are any entries you do not recognise. Errors are more common than most people expect. If something is wrong, raise a dispute with the agency directly. They are required to investigate with the lender.
If you have unsatisfied defaults you can clear, do so before applying. The change in status can make a meaningful difference to how your file is read.
How to apply for car finance with defaults through Motorly
Motorly works with a panel of specialist lenders who assess bad credit car finance applications, including those from people with defaults on their file.
The eligibility check uses a soft search, so there is no impact on your credit file at the eligibility stage. Apply online, receive a decision and choose your car from any approved UK dealer. No fees.
How many defaults can you have and still get car finance?
There is no fixed number that automatically rules you out. Lenders look at the age of the defaults, whether they are satisfied, how much they were for and what your credit file looks like now. Multiple old, satisfied defaults with a clean recent payment record may be easier to assess than a single very recent unpaid default.
Does paying a default improve your chances of car finance?
Paying a default updates the entry from outstanding to satisfied, which lenders view more positively. It does not remove the default from your file but it demonstrates the debt has been resolved.
How long does a default stay on your credit file in the UK?
Six years from the date it was recorded, after which it drops off automatically. Paying the default does not remove it early but updates the status to satisfied.
Can I get car finance with a default from last year?
It may be possible, but options are likely to be more limited than for older defaults. A default from the last year is recent, so lenders will look closely at whether it has been paid, whether any payments have been missed since and whether the proposed finance is affordable.
Does a satisfied default help with car finance?
Yes, compared with an unsatisfied default. It shows the debt has been cleared, even though the original credit problem remains visible on your file. It does not guarantee approval but it can improve how lenders assess the application.
What is the difference between a default and a missed payment?
A missed payment shows that an account has fallen behind. A default means the lender has formally recorded that the credit agreement broke down. Several missed payments typically lead to a default being registered.
Can I add a Notice of Correction to my credit file?
Yes, through Experian, Equifax or TransUnion. It lets you explain the circumstances behind an entry on your file. It does not remove the default or change the recorded data but it can give lenders additional context.
Will applying for car finance make my credit score worse?
It depends on the type of search. A soft search eligibility check should not affect your credit score and is not visible to other lenders in the same way as a hard search. A hard search may be recorded when you choose to proceed with a specific finance application.
If you have been searching for bad credit car finance from a direct lender, there is a good chance you have already been turned down somewhere, or you are worried you might be. Motorly is a car finance matching service. We connect people with brokers and lenders in the UK but do not lend money directly.
Going straight to a lender can sound appealing. No middleman. One company. A simpler process. Sometimes that is the right route.
But it is worth understanding what a direct lender actually does, how that compares with using a broker and why the difference matters more when your credit history is not perfect. This guide explains both options clearly so you can decide which route makes most sense for your situation.
What is a direct lender?
A direct lender is a company that lends its own money.
When you apply to a direct lender for car finance in the UK, they assess your application using their own lending criteria. If they approve you, they fund the agreement themselves. You deal with the same company throughout the process, from application and decision through to the finance agreement and repayments.
In the bad credit car finance market, direct lenders include specialist companies that focus on applicants with adverse credit histories. Companies like Moneybarn, Go Car Credit and Glenside Finance are examples of this type of lender. They have their own underwriting teams, their own risk models and their own view of what they are prepared to accept.
That can be useful if your circumstances match what that lender is looking for.
The limitation is that a direct lender has one set of criteria. Your application either fits their model or it does not. If it does not, the application is declined and there is no second lender within the same application that can take a different view. One of the most common things applicants tell us is that they had no idea why they were declined, because a direct lender is under no obligation to explain their decision.
What is a car finance broker?
A car finance broker does not lend its own money. Instead, a broker connects applicants with lenders on their behalf.
When you apply through a broker, your details are assessed by a panel of lenders. Each lender on that panel has its own criteria, products and risk appetite. The aim is to find the lender most likely to consider your specific circumstances. If one lender is not suitable, another may be.
Brokers are regulated by the Financial Conduct Authority and required to disclose how they are paid. A legitimate broker will use a soft search at the eligibility stage so your credit file is not affected until you choose to proceed. They will also be clear about whether they are acting as a broker or a matching service before you submit your details.
Motorly is a matching service. When you submit your details through Motorly, you are connected with brokers and lenders suited to your circumstances, including specialists in bad credit car finance.
The real difference for a bad credit applicant
If your credit history is clean and your income is straightforward, the difference between broker vs direct lender car finance may not feel significant. You may be accepted either way.
With bad credit, the difference matters considerably more.
A direct lender has one set of lending rules. Those rules will cover how they view CCJs, defaults, missed payments, IVAs, income type, employment history and how long ago the credit issues happened. If your application matches their criteria, going direct can work well. If it does not, you are likely to be declined.
That decline does not mean you cannot get car finance. It only means that one lender was not prepared to offer based on your profile. But if it came after a hard search, it now sits on your credit file, and if you then apply to another direct lender and get declined again, that pattern starts to count against you. Applicants often tell us they applied to two or three direct lenders before trying a panel, and each decline made the next application harder.
This is where a broker panel changes the picture. A broker assesses your application against multiple lenders at once. One lender may decline because your credit issues are too recent. Another may be more comfortable if your income is stable. One may not accept certain income types while another may. One may be stricter on CCJs while another focuses more heavily on affordability.
For bad credit applicants in particular, the line between approval and decline can be narrow. You are not just looking for any lender. You are looking for the lender whose criteria best match your circumstances. That is the practical advantage of a panel approach.
The trade-off is that a direct lender gives you one clear point of contact and a more direct relationship. A broker gives you broader coverage and saves you from applying to lenders one by one. For many bad credit applicants, that breadth of coverage is the difference between finding a yes and accumulating a string of nos.
Does going direct save you money?
A common assumption is that bad credit car finance with no broker must be cheaper because there is no middleman involved. That sounds logical, but it is not always how car finance works.
Brokers are paid commission by lenders. Regulated brokers must disclose commission arrangements and the commission should not increase the rate you are offered. FCA rules are clear on this point.
In practice, because brokers submit volume business to lenders, they sometimes negotiate access to rates that individual applicants cannot reach by applying directly.
In the bad credit market specifically, rates are driven primarily by your credit profile, affordability and the lender’s risk appetite, not by whether you applied directly or through a broker. The more meaningful variable is finding the lender whose criteria match your circumstances. That is what a panel approach is designed to do.
Should I trust a broker, and how do I know if one is legitimate?
The scepticism is understandable. If you have been declined before, the last thing you want is to hand your details to a company that is going to pass them around without being clear about what happens next.
A legitimate broker or matching service should be clear on a few things. They should tell you upfront whether the first stage uses a soft search or a hard search. They should be clear about how they are paid. They should be registered with the FCA. You can check any firm at fca.org.uk. And they should not charge you a fee just for submitting an application.
One of the most common misconceptions we see is that any broker involvement automatically means a worse deal. In reality, the FCA rules that govern commission mean a regulated broker cannot inflate your rate. Because brokers place volume business with lenders, they sometimes have access to products that are not available to individual applicants applying on their own.
If a site is vague about search types, unclear about commission or asks for payment before you have received any offer, those are reasons to be cautious.
Transparency at the start of the process is usually a reasonable indicator of how the rest of it will go.
When a direct lender might be the better route
There are times when applying to a car finance direct lender with bad credit makes sense, and it is worth being honest about them.
If you have researched a specific lender and know their criteria match your situation, for example a lender that specialises in applicants currently in an IVA or one that accepts benefits as primary income, applying direct can be a reasonable choice. You know what you are applying for and why.
Going direct can also appeal if you prefer dealing with one company from start to finish. Some people like the simplicity of knowing exactly who is assessing the application and who will manage the agreement.
A direct lender may also be worth considering if you have already used a broker panel and were declined. In some situations, a lender with more manual underwriting may review your case differently where automated systems have not.
It is also worth knowing that guarantor car finance can be a practical alternative if both routes have been exhausted, where a creditworthy guarantor supports the application.
The point is not that one route is always better. It is that the right route depends on your circumstances.
How Motorly works for bad credit applicants
Motorly matches people with brokers and lenders that consider applicants with poor or limited credit history, including people with missed payments, defaults, CCJs, IVAs, thin credit files or previous finance declines.
When you submit your details, they are assessed using a soft search. Checking your options does not affect your credit score.
If a match can be made, you will receive a decision. If not, you will be told, and you can then decide whether a specific direct lender, guarantor option or another route may be worth exploring.
There is no fee to use Motorly. The process takes a few minutes and there is no impact on your credit file unless you choose to proceed with an offer.
If you have been declined before or you are not sure which lender is right for your circumstances, the panel approach is usually the better starting point. Motorly’s matching process takes a few minutes and uses a soft search, so there is no impact on your credit file until you choose to proceed.
What is the difference between a direct lender and a broker for car finance?
A direct lender provides the finance itself. It assesses your application using its own criteria and funds the agreement if you are approved.
A broker does not lend its own money. Instead, it submits your details to a panel of lenders to find one that may be suitable for your circumstances.
For bad credit applicants, the main difference is lender choice. A direct lender gives you one decision from one company. A broker panel gives your application access to multiple lenders at once.
Do direct lenders charge more than brokers for car finance?
Not necessarily. The rate you are offered is based on your credit profile, affordability, the lender’s criteria and the finance product. Broker commission should not increase the rate you are offered. FCA rules require this.
Going direct does not automatically mean a cheaper deal. The most important factor is finding the best direct lender for car finance with bad credit, the one whose criteria best fit your situation.
Can I get car finance direct with a CCJ?
You may be able to, but it depends on the lender. Many lenders treat a CCJ that is more than three years old very differently to a recent one, and a satisfied CCJ is viewed more favourably still. The age and status of the judgment often matters as much as the amount.
Some lenders will consider applicants with CCJs if the CCJ is older, satisfied or your current affordability is strong. Others may decline automatically.
A broker panel can be useful here because different lenders treat CCJs differently. If one lender says no, another may still consider your application.
Does applying to a direct lender affect my credit score?
It depends on whether the lender uses a soft search or a hard search. A soft search does not affect your credit score and is only visible to you. A hard search is recorded on your credit file and may be seen by other lenders.
Before applying to any direct lender for car finance in the UK, check which type of search they use at the first stage. This matters especially if you are making several applications in a short period.
Are there direct lenders that accept very bad credit?
Some direct lenders specialise in applicants with poor credit, but acceptance is never guaranteed. Each lender has its own criteria covering income, affordability, employment, address history, recent credit behaviour and the type of adverse credit on your file.
If your credit history is very poor, starting with a matching service or broker panel may help you understand whether any lender is likely to consider you before applying directly elsewhere.
Is it better to use a broker or go direct for bad credit car finance?
It depends on how much you know about which lender is right for you. If you have identified a specific lender whose criteria suit your circumstances, applying direct can make sense. If you are not sure, a broker panel or matching service gives you broader coverage without the risk of accumulating hard searches across multiple direct applications.
What happens if a direct lender declines my application?
It means your profile did not meet that lender’s criteria at that time, not that you cannot get car finance elsewhere. Another lender may take a different view.
Before making further applications, check whether the previous one involved a hard search. Too many hard searches in a short period can make future applications more difficult.
Final thoughts
Searching for bad credit car finance from a direct lender makes sense. If your credit history is not perfect, you want a route that feels clear, fair and gives you a realistic chance of approval.
Direct lenders can be a good fit when you know their criteria match your circumstances, or when you prefer dealing with one company throughout.
But if you are not sure which lender is right for you, applying to direct lenders one at a time carries a real risk. Each declined application can make the next one harder. A matching service or broker panel gives your application wider exposure and helps connect you with options that are more likely to consider your profile.
Motorly’s view is shaped by working with a range of brokers and lenders, which is why we think broader coverage usually beats applying to one place at a time. For many bad credit applicants, the strongest first step is not guessing which direct lender might say yes. It is checking your options across a wider panel first.
If you have been declined for standard car finance and come across the term pay as you go car finance, you are probably wondering whether it is the answer — or whether you are running out of options altogether. This guide explains what PAYG actually is, who it suits and why, for many people searching for bad credit car finance in the UK, a specialist broker panel may already offer more than you think.
At Motorly, we do not offer pay as you go car finance directly. We want to be clear about that from the start.
What is pay as you go car finance?
Pay as you go car finance, often shortened to PAYG car finance, is usually a type of hire purchase agreement. You pay a deposit, borrow the rest of the cost of the car and then make regular repayments over an agreed term. Once the final payment has been made, you own the car outright.
The main difference between standard HP and pay as you go car finance is the black box.
After you have been approved, a small device is fitted to the car — usually in the glovebox or under the dashboard. It is a payment reminder device, and this is worth being clear about: a PAYG black box works differently to the telematics devices used by some insurance providers. It does not track your speed, your routes, your cornering or your driving habits in any way. This is one of the most common questions we get from customers who have seen PAYG mentioned online. The box has one job: to confirm payment status and, if necessary, restrict use of the vehicle when stationary.
Typically, the device changes indicator colour before your monthly payment is due. You may also receive a text reminder. If you miss a payment and do not resolve it within the lender’s grace period — typically 30 days — the lender may be able to remotely immobilise the car while it is stationary. It will not cut out while you are driving.
You may also see this type of finance described as black box car finance, pay as you drive finance, pay weekly car finance or PAYG car finance. In practice, most modern agreements use monthly repayments rather than weekly ones, so the pay weekly label can be misleading.
Who is pay as you go car finance designed for?
Pay as you go car finance is usually aimed at people who find it difficult to get approved for standard car finance. That can include people with missed payments, defaults, CCJs, a discharged bankruptcy or a very limited credit history. The black box gives the lender extra confidence because they have a way to restrict use of the vehicle if repayments stop, which allows them to approve applicants they might otherwise decline.
It is also sometimes marketed to people who prefer smaller, more regular payments — though as noted above, weekly repayments are not standard in most PAYG agreements, so it is worth checking the actual schedule before applying.
If your credit history is clean, or only lightly affected by older issues, PAYG is unlikely to be the best starting point. A standard HP agreement through a specialist broker may give you more choice, fewer restrictions and potentially a better rate.
What are the downsides of pay as you go car finance?
PAYG car finance can be useful in the right situation, but it comes with trade-offs worth understanding before you commit.
Rates are typically higher than standard HP — in many cases meaningfully so, with some PAYG agreements carrying APRs well above what specialist bad credit HP lenders offer for comparable applicants. Easier access to finance can come at a price, and that shows up in the total amount repayable over the term.
Availability is also limited. PAYG is offered by a handful of specialist lenders in the UK rather than the broader panel a specialist broker might work with, which is part of why rates tend to be less competitive.
Then there is the black box itself. Some people find the reminder system helpful; others find it uncomfortable knowing a device is fitted to the car. Either way, it stays in place until the final payment has been made.
Missing a payment and not resolving it within the grace period can result in the car being disabled while stationary. That is the mechanism that makes the product viable for lenders, but it is a real consequence for the borrower, particularly if you rely on the car for work.
Vehicle choice may be more limited too. Many PAYG lenders work with their own approved dealer networks, which can restrict where you buy from and what stock is available.
Motorly does not offer pay as you go car finance — here is why that might not matter
Motorly is a specialist car finance broker. We do not fit black boxes and we do not offer pay as you go car finance directly.
But the reason most people search for PAYG is rarely because they specifically want a black box. It is because they are worried about getting accepted. You may have poor credit, a CCJ or defaults on your file. You may have been declined before. Or you may simply not know whether standard lenders would consider you.
That uncertainty leads a lot of people to assume PAYG is their only route, when in many cases they have not yet tried a panel approach at all. In our experience, many applicants who come to us expecting to be declined are matched with a lender on the first application.
When you apply through a broker like Motorly, your application is assessed by a panel of lenders — some of whom work specifically with people who have bad credit, thin credit files or previous financial difficulties. If one lender says no, another may say yes. Different lenders look at applications in different ways, which can open up more options than approaching a single provider directly, often at a more competitive rate and without a black box requirement.
For many people searching for pay as you go car finance with bad credit, this route gets them into a car without the restrictions a PAYG agreement brings. It is worth checking before committing to a black box provider.
Can you get car finance with bad credit without a black box?
Yes, many people can — and a black box is not a requirement to get there.
A lot of people searching for pay as you go car finance are really asking a different question: can I get car finance at all with my credit history? In many cases, the answer is yes.
The UK bad credit car finance market is well established. Specialist lenders in this space look at the full picture rather than making a decision on a credit score alone. They consider income, employment stability, affordability, residential history and how recent any credit problems are.
A CCJ from three years ago with a clean record since is a very different application to one from six months ago, and lenders treat them differently. The same goes for a satisfied default versus an active one. In our experience, the gap between adverse events and the application date matters too — someone who had a difficult period two or three years ago but has since maintained a clean record and stable employment is often in a stronger position than their score suggests.
That does not mean approval is guaranteed — no responsible lender or broker should promise that. But it does mean a black box is often not the only route, and frequently not the best one.
Before applying, check your credit file so you know what lenders are likely to see. The three main credit reference agencies in the UK are Experian, Equifax and TransUnion — you can check your report with each of them, and some offer free access. Look for errors, outdated information or accounts that should have been marked as settled. If anything looks wrong, raise a dispute with the relevant agency. If you have an unsatisfied CCJ or outstanding default, addressing it before you apply may improve your options.
PAYG car finance may be worth exploring if you have been declined by multiple mainstream and specialist lenders, your credit file has recent or serious adverse history, or you actively want a payment reminder system to help you stay on track.
Standard HP through a specialist broker is usually the better starting point if you have not yet tried a panel approach, your credit issues are older rather than recent, your income is stable, or you want more flexibility over which dealer you buy from.
Many people who search for black box car finance or pay as you go car finance do so because they assume standard finance is already off the table. That assumption is worth testing before you commit to a PAYG provider.
How to apply for car finance through Motorly
Applying through Motorly takes a few minutes and does not affect your credit score at the eligibility stage.
Step one: Complete a short online application with your personal and financial details. This gives lenders the information they need to assess your circumstances.
Step two: Your application is matched against a panel of lenders, including specialist options for people with poor credit, CCJs or previous finance difficulties. If one lender is unable to help, another may be able to.
Step three: If you are offered finance, you can review what is available and find a car from any approved dealer across the UK. You are not limited to a single dealer network.
Is pay as you go car finance the same as black box car finance?
Yes, the terms refer to the same product. Pay as you go car finance is a hire purchase agreement where a black box device is fitted to the car. It acts as a payment reminder and can allow the lender to immobilise the vehicle if payments are missed. You may also see it called pay as you drive finance or pay weekly car finance, though monthly repayments are standard in most modern agreements.
Can I get pay as you go car finance with a CCJ?
You may be able to, depending on the lender and your wider circumstances. PAYG finance is often aimed at people with poor credit, including those with CCJs or defaults. That said, it is not the only option. Specialist HP lenders may also consider applicants with a CCJ, particularly if it is older, satisfied or your recent credit history has improved. It is worth checking both routes before committing to a PAYG provider.
Does the black box track my driving?
No, and this is a common misunderstanding. The black box in a PAYG agreement is a payment device. It does not monitor your speed, record your routes or track your driving behaviour. Its functions are to act as a payment reminder and, if the lender instructs it following an unresolved missed payment, to immobilise the vehicle when stationary.
What happens if I miss a payment on PAYG car finance?
If you miss a payment, the lender will usually contact you and give you time to resolve it. If the payment is not brought up to date within the agreed grace period — typically around 30 days — the lender may be able to immobilise the car while stationary. The exact terms depend on your agreement. Contacting your lender as soon as you think you might miss a payment is the most practical step.
Can I get car finance with bad credit without a black box?
Yes, in many cases. Specialist HP lenders may consider people with missed payments, defaults, CCJs or a thin credit file. They tend to look at the full picture — income, employment, affordability and how recent the credit issues are — rather than making a decision on a score alone. See our bad credit car finance guide for more.
How does pay as you go car finance affect my credit score?
Like any HP agreement, PAYG car finance will appear on your credit file. Making payments on time can help demonstrate responsible borrowing and build your credit history. Missing payments will harm it. The black box itself does not interact with your credit file — it is a risk management tool for the lender, not a reporting mechanism.
Is PAYG car finance more expensive than standard HP?
Generally, yes. PAYG lenders accept higher-risk applicants, and APRs tend to reflect that. The smaller pool of PAYG providers also limits competition on rates. That is why it is worth checking what a specialist broker panel can offer before committing to a PAYG agreement — for many applicants, standard HP turns out to be more accessible than they expected.
Do I need a deposit for pay as you go car finance?
Most PAYG agreements do require a deposit, as does standard HP. The amount varies by lender and the value of the vehicle. If a deposit is a barrier, it is worth raising this when you speak to a broker or lender — some have more flexibility than others depending on your overall application.
If anything in this article has made you question whether PAYG is really your only option, the most practical next step is to check what a specialist broker panel can offer. Many people searching for pay as you go car finance with bad credit find they have more choices than they expected — and a soft credit check with Motorly will not affect your score.